The five decisions behind every marketplace payment, and where a payment platform can take them off your plate.
Key takeaways
- Every marketplace payment turns on five decisions: seller accounts, pay-ins, take rates, splits, and payouts.
- Building payments in-house invites licensing risk and complexity – multi-seller splits, partial refunds, and negative seller balances each need their own logic.
- Match take rates and account types to your seller economics, and keep them configurable for later changes.
Every marketplace payment runs through the same five decision points: how sellers get verified and paid, how money comes in, what you charge, how it splits, and how money goes back out.
Managing all five of these yourself is a lot of infrastructure to build and maintain - and a payment platform can automate most of it for you.
This guide is a breakdown of what those five decisions look like in practice, where marketplaces like Etsy, Uber, and Amazon land on each one (and why), and where using a marketplace payment platform can take the weight off your team.
What goes into every marketplace payment, and what you can automate with a payment platform
From money coming in to money going back out, here's each decision, what's at stake if you get it wrong, and where a marketplace payment platform can automate it for you.
A marketplace payment platform is the infrastructure layer that handles seller onboarding, pay-ins, fee splits, compliance, and payouts for a multi-seller marketplace - so the marketplace doesn't have to become a licensed financial institution itself.
1. Connected accounts: choosing how (and how fast) your sellers get paid
The first decision is when you verify sellers. Front-load KYC/KYB at signup and you protect yourself from the moment sellers sign up, but you will lose sellers who are put off by identity admin before they've listed anything for sale.
This is a real concern: 74% of potential customers will switch to a competitor if onboarding is too complicated (per research cited by ConnectPay) - and for marketplaces, that friction lands right at seller signup.
The other option is to require KYC/KYB at the point of payout instead. When you take this road, onboarding becomes faster, but until they complete KYC/KYB, you are carrying unverified sellers on your marketplace.
Even the biggest marketplaces don't verify instantly. Amazon's seller verification takes 7-14 days, and Walmart Marketplace runs 1-2 weeks. Automated KYC for individual sellers can run in minutes, while KYB usually takes 1-5 business days.
The second decision is account type.
A full connected account gives a seller control, their own balance, and choice over when to withdraw, and often the ability to hold funds across multiple currencies.
If you're running a marketplace with high-earning, repeat sellers who expect to manage their own payout schedule - something like Etsy or Fiverr - this is usually the right choice. Sellers may churn if they feel locked out of their own money.
Marketplace seller KYC typically runs $0.30 to $1.60 per verified seller. At scale, the account type you choose matters: a high-touch, full-featured account for every seller adds real onboarding cost per seller, on top of verification itself.
A lighter, ledger-style account swaps that level of control for faster, cheaper onboarding.
In these cases, the seller doesn't get full autonomy over their funds. But verification is often lighter, and you get sellers onboarded and transacting much faster (and at a much lower cost per seller on your end).
This account style makes more sense if your marketplace has high-volume low-earning sellers, like Uber or DoorDash, where gig-economy or micro-transaction models mean full account infrastructure for every driver would cost more than most of them individually earn.
Build this yourself and you're maintaining your own KYC/KYB integration, sanctions screening, and two separate account infrastructures - one lightweight, one full-featured - plus the logic to move a seller between them as they grow.
A platform that handles verification and lets you assign account tiers per seller does that work for you: you can onboard fast and verify at payout for most sellers, while still offering full accounts to the sellers who need them, without maintaining two systems yourself.
2. Marketplace pay-ins: choosing how money gets in the door
Once a seller is onboarded with a connected account, your platform's next job is getting money into that account. How it lands there depends on several choices that you make for your marketplace payment mechanics.
Payment capture timing
Capture timing is a cash-flow-vs-refund-risk tradeoff either way.
If you choose to capture that payment instantly, then you lock in that revenue the moment a buyer commits to a sale.
This is great for cash flow, but if the order falls through, you have to issue a refund, not just release a hold.
Delay the capture until the order ships instead, and you avoid that problem. But in this case there's a chance that you lose the sale altogether.
Picture this: a buyer pays with a debit card for a $50 item on Friday, authorized instantly. Debit holds can release in as little as 1-2 business days depending on the issuing bank, far shorter than the 7-day window standard on credit cards. If the seller doesn't ship until Monday, that hold may already be gone.
Where funds sit, and who's liable
Where funds sit before the split matters more than you may think.
Some providers hold funds in their own regulated, neutral account until they're split and paid out. This means that your marketplace's own bank account never holds the full pay-in, it only receives its own part of the split.
Other providers route everything through your own marketplace's account first, which puts you briefly in legal possession of buyer and seller money.
In the US, holding customer funds, even briefly, before passing them along can be enough to require a license in every state you operate in. New York alone requires a $500,000 surety bond. Licensing runs state by state, not once nationally, so a marketplace operating across the US could be looking at seven figures in bonds and net-worth requirements combined.
Currency conversion: in-house or bolted on?
Currency conversion is a build vs. bolt-on decision.
Native conversion inside your payment provider happens automatically, in the background, as part of the pay-in itself. The buyer pays in their own currency, the seller gets paid in theirs, and your provider handles the exchange rate and settlement.
ecomflow, a 3PL fulfillment platform, offers local payment methods with Whop. "They have more methods to pay, which is a great benefit for them," says Nolan Rook, ecomflow CTO.
Bolt on a separate FX provider instead and you are now adding a second system to the payment flow.
In this scenario, money moves through your primary processor, then gets handed off to a separate FX layer for conversion, then continues on to the seller.
That's a lot of moving parts, and each handoff is an opportunity for delayed conversion, mismatched transaction IDs, shifting rates, and FX markups.
Choosing the second option here only really becomes necessary in one use case: your primary payment provider doesn't natively support a currency or market that you need to reach.
Native, in-house conversion can run as low as 1%, while stacked or less-optimized setups often land at 3-5% more on the same transaction.
Marketplace payment method coverage
None of that works if the buyer can't pay in the way that they want to.
Cards are still the default almost everywhere, but they're no longer the be-all-and-end-all. Digital wallets like Apple Pay and Google Pay are closing that gap fast, especially on mobile, since they skip manual card entry.
Selling cross-border? Local payment methods are essential here, not optional. A buyer in the Netherlands wants iDEAL, a buyer in Poland wants BLIK, and a buyer in Brazil may expect Pix.
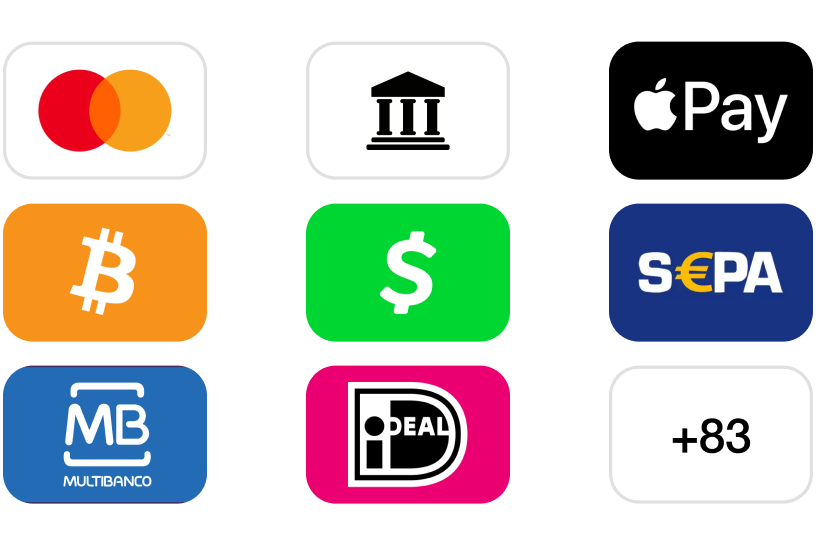
Build all of this yourself and you're the one managing your own FX relationships and integrating each local payment method individually.
A platform that handles native FX and bundles local payment methods into one checkout removes the burden from your end.
3. Take rates (how to decide what to charge)
Most marketplaces don't get their take rate right the first time. But more importantly, they don't build in room to change it.
- A fixed take rate is a flat fee per transaction, regardless of order size. This is the most straightforward, predictable take rate, but it hits low-value sales harder and barely registers on high-value ones.
- A variable take rate is a percentage of the transaction, rather than a fixed fee, so it automatically scales with order size. This is the most common method, and has flexibility to vary by category or seller tier, or be used as a growth incentive (e.g. lower rates for new sellers to convince them to use your marketplace).
- A compound take rate combines both fixed and variable fees. It is a fixed fee plus a percentage on top. This guarantees a baseline of revenue while still capturing more on larger sales.
Etsy runs a compound model: a $0.20 listing fee plus a 6.5% transaction fee, with payment processing (3% + $0.25 in the US) on top. eBay charges a 13.6% final value fee in most categories, plus $0.30 or $0.40 per order.
Fiverr splits its take across both sides: sellers keep 80% of each order, and buyers pay a 5.5% service fee.
A single percentage works best when order sizes sit in a narrow band. Across a $10 to $10,000 range, one rate is too thin to cover fixed costs on small orders and too heavy on large ones.
This is why Fiverr adds a $3.50 fee to orders under $200, and eBay drops to 2.35% on the part of a sale above $7,500.
Here's what five major marketplaces publish on their US fee pages, as of October 2026:
| Marketplace | Category | Seller pays | Buyer pays | Model |
|---|---|---|---|---|
| Etsy | Handmade and vintage goods | $0.20 listing fee + 6.5% transaction fee + 3% + $0.25 processing | – | Compound |
| eBay | General goods | 13.6% in most categories (up to $7,500) + $0.30–$0.40 per order | – | Compound |
| Fiverr | Freelance services | 20% | 5.5% + $3.50 on orders under $200 | Two-sided |
| Airbnb | Short-term stays | 15.5% for most hosts (single fee), or about 3% (split fee) | 14.1–16.5% (split fee only) | Moving to host-only |
| Uber Eats | Food delivery | 20%, 25%, or 30%, by plan | Customer fees vary by order | Tiered plans |
Published fees aren't the same as a realized take rate (total marketplace revenue divided by total sales). For revenue-based figures by industry, see our take rate benchmarks.
What a 10% take rate actually nets
Your headline take rate isn't what you keep. Here's a $100 order at a 10% take rate on Whop's standard domestic card rate, with your platform covering the fees (the transfers flow), a 3% refund rate, and a 0.5% dispute rate. The example assumes you recover the seller's share each time:
| Line | Per $100 order |
|---|---|
| Commission (10%) | $10.00 |
| Processing fee (2.7% + $0.30) | –$3.00 |
| Payout fee, if you cover it ($2.50 next-day ACH, shared across a 10-order weekly payout) | –$0.25 |
| Refunds (3% of orders lose the $10 commission and the $3.00 fee) | –$0.39 |
| Disputes (0.5% of orders add a $15 dispute fee to the lost commission and fee) | –$0.14 |
| What you keep | $6.22 (6.2% effective take rate) |
That's nearly 40% of the headline rate gone before your own costs, which is why your take rate needs room to move.
Who you charge matters just as much as how much. Charging buyers directly (by issuing a service fee on top, like Fiverr does) works for service and ticketing marketplaces, where this reads as normal.
But try to do this on a regular goods marketplace, and this will cause sticker shock at the final screen.
Building a take rate yourself means that every rate change – new tiers, new categories, switching from variable to compound – means an engineer has to update the logic and ship it to production.
When you use a payment platform where splits and commissions run through the API as configurable logic rather than hard coded percentages, changing your rate by tier, category, or individual seller is much lower lift - a config change, not a code change.
4. Split payments: who gets paid, and when
For a single-seller sale (the likes of Etsy or Fiverr, where a checkout is one buyer paying one seller) splitting is simple. A buyer pays $100 for an item, your marketplace takes a $10 commission cut, and $90 gets sent to the seller's connected account.
Nothing about that requires much infrastructure.
Multi-seller orders are where this gets more complicated (and the real engineering decision shows up).
Amazon's marketplace works this way: one order can include products from several third-party sellers, all in one cart and paid through one checkout.
Say a buyer spends $100 (a $60 item from seller A and a $40 item from seller B), and you take 10%. That one payment has to become $54 for seller A, $36 for seller B, and $10 for you.
Then add processing fees and refunds. Here’s that $100 order as a ledger, run as one charge to your platform account followed by a transfer to each seller, using a 2.7% + $0.30 card fee:
| Step | What happens | Platform | Seller A | Seller B |
|---|---|---|---|---|
| Charge | Buyer pays $100. The $3.00 processing fee comes out. | $97.00 | – | – |
| Transfers | You transfer $54 to seller A and $36 to seller B. | $7.00 | $54.00 | $36.00 |
| Partial refund | Buyer returns seller B's $40 item. You refund the full $40 (seller B's $36 plus your $4 commission). The $3.00 fee isn't returned, so you're $33 out of pocket until you recover seller B's share. | –$33.00 | $54.00 | $36.00, or $0 if already withdrawn |
| Recovery | You recover seller B's $36 from their balance, or from their next payout if they've withdrawn. | $3.00 | $54.00 | $0, or owes $36 until repaid |
Seller A’s $54 never moves. You end up with $3.00, your $6 commission on seller A’s item, minus the $3.00 processing fee on the original charge.
Three decisions sit inside that ledger:
- Who absorbs the processing fee: Above, you do, so your $10 commission nets $7.00 before any refund. Allocate it pro rata instead and seller A carries $1.80, seller B carries $1.20, and you keep the full $10.
- What happens to fees on a refund: The processing fee on the original charge isn’t returned, so a refunded order costs you that fee as well as your commission.
- How you recover a seller’s share: If seller B has already withdrawn, they owe you $36 – a negative seller balance you need a rule for, usually deducting it from their next payout.
Two ways to run the split on Whop
Whop gives marketplaces two payment flows, and the right one depends on how many sellers are in a checkout.
- Direct charges: the checkout is created on the seller's connected account, with an application fee for you. The seller pays Whop's fees and handles refunds and disputes. This fits single-seller orders: a $100 order with a $10 application fee sends $90 to the seller's account.
- Transfers: the buyer pays your platform account, and you transfer each seller's share via the API once the order settles. Your platform pays Whop's fees, handles refunds and disputes, and is the merchant of record for the original payment. This is the flow for multi-seller carts like the one above.
Either way, the money movement (charges, application fees, transfers, and full or partial refunds) runs through Whop's API, so there's no payment infrastructure for your team to build.
What your team owns is the business logic on top: each seller's share, when you release it, and how you recover a refunded seller's share.
5. Marketplace payouts (getting money back out)
How you structure your marketplace payouts is one of the most consequential decisions that you can make.
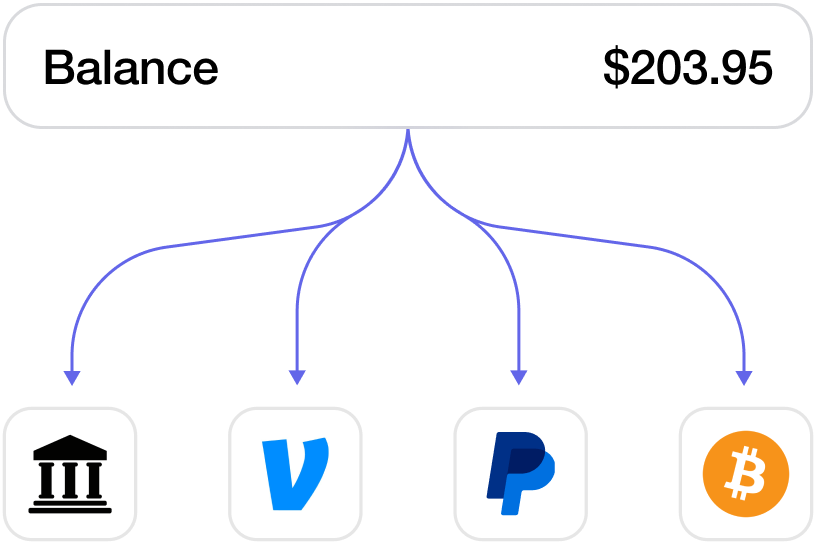
Scheduled payouts: predictable, but sellers wait
Scheduled marketplace payouts (daily, weekly, monthly) are the default for most marketplaces, because they're predictable for sellers and easy for marketplaces to reconcile.
But it means that a seller's share sits in limbo before they can access it - this is where competitors offering faster access start to look more attractive.
Real-time (instant) payouts: sellers want it, but who pays?
Instant payouts fix that, sending the funds the moment they're triggered, sometimes within minutes. Sellers love this (understandably - they get their money faster).
But speed always costs more: instant payout rails typically charge a percentage plus a flat fee, versus a low flat rate for standard ACH. Someone has to absorb that cost: you, or the seller as an optional, paid upgrade over free scheduled payouts.
Manual payouts: control at the cost of automation
Manual payouts sit apart from both, triggered on demand, either by the seller requesting a withdrawal or you initiating one. This gives you more control over timing, at the cost of the automation that scheduled or instant payouts provide.
Where sellers manage their payout - balance, withdrawal, methods, status - is another decision that often gets overlooked.
Embedded payouts keep the whole thing inside your own product. A hosted page somewhere else is a jarring handoff after a seller has spent the whole time on your platform.
Marketplaces that choose to build payouts themselves must manage multiple payout rails, the cost logic for who absorbs instant-payout fees, and their own embedded UI for balance and withdrawal management.
A platform that offers all three payout types natively - with embeddable components for the entire experience - means sellers get the payout speed and interface that keeps them transacting on your marketplace, without your team building and maintaining separate systems for each.
Per a Visa/PCMI survey of 2,800 marketplace sellers, 70% would consider switching platforms if offered better payout solutions, and 94% say payout speed directly impacts their business. Payout experience isn't just about getting the money out, it's part of why a seller stays on your marketplace at all.
Building payments yourself vs choosing a marketplace payment platform
A handful of marketplaces have gone the full-build route - Amazon and Airbnb both run their own licensed payment subsidiaries - but that's years of infrastructure and compliance work, not a decision most marketplaces can justify making themselves.
Instead, most marketplaces build on top of a payments platform rather than becoming a licensed financial institution themselves.
The rest of this guide covers what to look for in a marketplace payment platform, and the top platforms of 2026.
What to look for in a marketplace payment platform
Here's what you need to check before you commit to one.
Coverage: does it reach where your sellers are?
Coverage on the buyer side doesn't automatically mean coverage on the seller side. A platform advertising coverage in 40+ countries doesn't work if none of your sellers and buyers are actually in them.
Check where your buyers and sellers are today and where you plan to expand in the future, then look at platforms that support payouts, local currencies, and local payment methods in those markets.
Compliance: what's handled for you, and what's handed back to you?
KYC and KYB cover onboarding, but compliance doesn't stop there - ongoing sanctions screening and tax reporting obligations (such as 1099-Ks in the US or DAC7 in the EU), are requirements that your marketplace has to meet, regardless of whether or not your team is equipped to handle them.
One of the main differences in marketplace payment platforms is who handles the compliance work. Some platforms handle all of this in the background for you. Others give you a compliance checklist and put the responsibility in the hands of your team.
When analyzing platforms, check whether the platform simply offers templates, or takes care of the busy work for you.
In September of 2025, Temu paid a $2 million penalty to the DOJ and FTC - the first enforcement action under the INFORM Consumers Act, after failing to properly verify and disclose information about its third-party sellers. The law requires marketplaces to collect and verify identifying information from sellers with 200+ transactions and $5,000+ in annual revenue (and to disclose that identity to buyers once a seller passes $20,000).
How flexible is the take rate?
Your take rate needs room to change as you scale.
When evaluating a platform specifically, ask: can you set different rates by seller tier, category, or volume? Can you charge buyers as well as sellers if your model calls for it? Can you change the structure from variable to compound, blending a flat fee with a percentage, without renegotiating your entire integration?
Some platforms lock you into one rate structure at setup, with a single percentage applied uniformly, leaving no room to differentiate.
That's fine if your pricing will never need to change – but in most situations (as has been the case for Airbnb and Etsy) – it will.
Who legally owns the transaction?
This comes down to who's the merchant of record.
If your marketplace is the merchant of record, your business name is what appears on the buyer's bank statement, and you're the one liable for chargebacks and regulatory responsibility for the sale itself (tax collection, refund policy, dispute resolution).
If your payment platform is the merchant of record itself, they absorb that liability on your behalf. Chargebacks route through them, disputes get handled under their compliance framework, and transactions on bank statements read as their name, not yours.
Global chargeback volume is projected to climb from 261 million disputes worth $33.8 billion in 2025 to 324 million worth $41.7 billion by 2028. (Mastercard)
Being the merchant of record yourself gives you more control, but it also means that you carry the cost and effort of things going wrong.
Top 5 marketplace payment platforms for 2026
Before we get into the full breakdown for each payment platform, here's a handy table to compare the top 5 at a glance:
| Platform | Pricing | Compliance | Payouts | Best for |
|---|---|---|---|---|
| Whop | 2.7% + $0.30 | Handled by Whop | Scheduled, instant, manual | Payments, payouts, KYC, and tax in one API |
| Stripe Connect | 2.9% + $0.30, plus $2 per active account and 0.25% + $0.25 per payout if you set pricing | Split | Scheduled, instant, manual | Engineering teams that want full control |
| Adyen for Platforms | Not published | Yours | Managed or custom | Enterprise platforms in the US and Europe |
| Airwallex | Not published | Split | Local + SWIFT | Multi-currency payouts across many countries |
| PayPal for Platforms | Not published | Handled by PayPal | Automated multiparty | Buyers who expect PayPal at checkout |
Whop
Whop is the end-to-end API for running a business online, covering everything from checkout to payouts, and it extends cleanly into platform and marketplace use cases.
For marketplaces specifically, Whop covers the full loop: connected accounts, pay-ins, take rates, split payments, and payouts, all native to one system.
- Coverage: payments in 195 countries, with 100+ payment methods including BNPL and crypto.
- Connected accounts: onboarded and verified directly through Whop. KYC is not required upfront - only once a seller is ready for their first payout - so onboarding stays fast, but sellers must be verified to access funds.
- Compliance: KYC and payout compliance are handled by Whop as part of onboarding and payouts, including W-9/W-8 collection and 1099s for payout recipients. Whop's optional tax service (2% per transaction when tax is collected) can calculate, collect, and remit tax in the US, EU, and UK.
- Take rate: application fees on direct charges, or transfers from your platform account for multi-seller orders, with per-seller and per-transaction fee logic set through the API.
- Payouts: scheduled, instant, and manual options, via next-day ACH, instant bank deposit, crypto, Venmo (US recipients), bank wire, and local bank transfers.
- Embedded elements: pre-built KYC and payout components can be embedded directly into a platform's own product.
- Choose Whop if: you want payments, payouts, KYC, and tax handled in one API, with published pricing and payout components you can embed for your sellers.
Pricing: 2.7% + $0.30 for domestic card payment acceptance (Whop's standard rate), plus payout fees from $2.50 per next-day ACH payout. No sales call required to start, but enterprise customers can book a call with the Whop sales team for custom pricing.
Stripe Connect
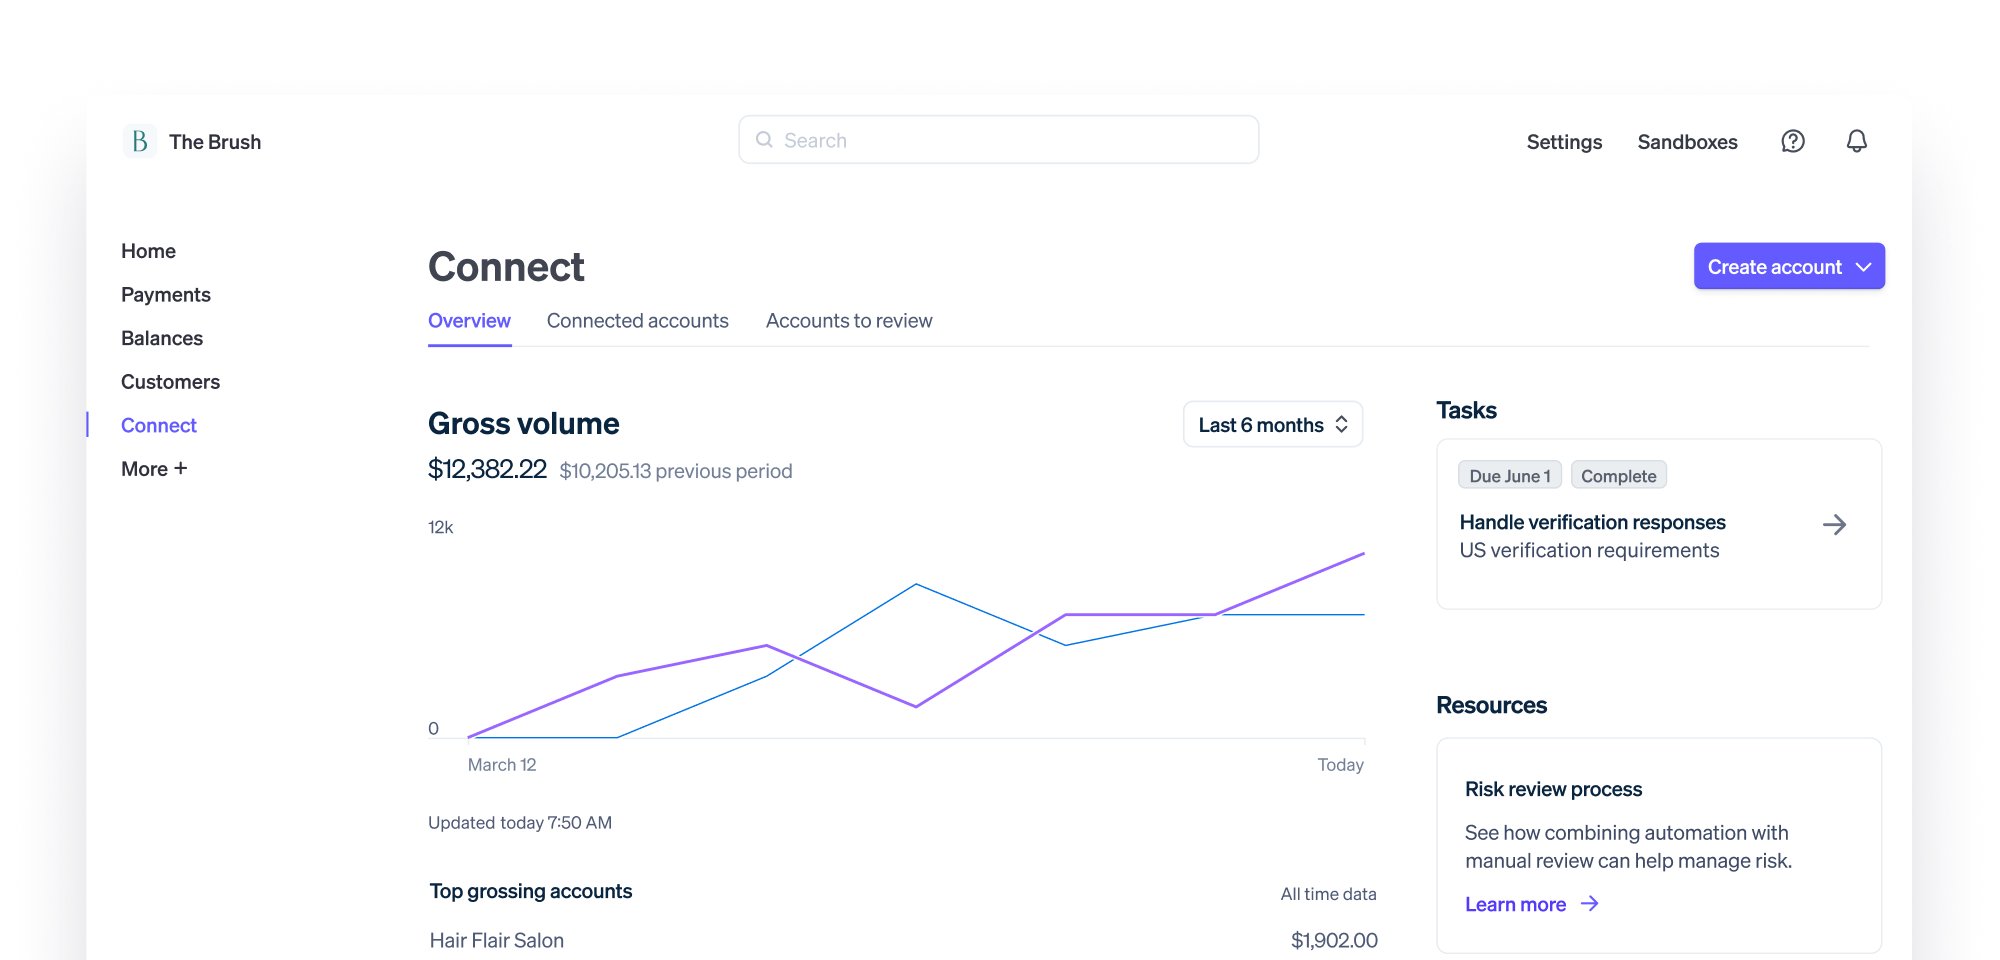
Stripe Connect is Stripe's dedicated infrastructure for platforms and marketplaces, built on top of Stripe's general payments stack.
- Coverage: payouts in 118+ countries, support for 135+ currencies. Self-serve cross-border payouts depend on where your platform is based: platforms in the US, UK, EEA, Canada, or Switzerland can pay connected accounts in any of those regions.
- Connected accounts: Stripe's current model uses controller properties rather than fixed account types, letting platforms configure dashboard access, who's liable for fraud and disputes, and who pays processing fees individually. KYC information must be collected and verified before an account can accept charges or receive payouts.
- Compliance: Stripe collects and verifies KYC information as part of onboarding, with verification flows that adjust by country, business type, and account capabilities. Who's responsible for 1099 filing depends on who controls pricing.
- Take rate: application fees are collected automatically per transaction via the API, supporting per-seller and per-transaction logic.
- Payouts: scheduled, instant, and manual options, via bank transfer, debit card, and more.
- Embedded elements: embeddable components for onboarding, payments, payouts, and reporting.
- Choose Stripe Connect if: your platform is based in one of Stripe's cross-border regions and you have engineers to configure charge types, onboarding, and fee logic yourself.
Adyen for Platforms
Adyen for Platforms is Adyen's answer to onboarding sellers, splitting payments, and managing payouts.
- Coverage: onboarding is supported across 39 countries and regions, primarily in the US and Europe/EEA.
- Connected accounts: sellers are onboarded as sub-merchants under an account holder resource.
- Compliance: Adyen has tools that support KYC, sanctions checks, and watchlist screening to automate parts of the processes. However, you are directly responsible for managing the relationship with your users, including compliance.
- Take rate: marketplace commission can be set as a fixed amount, a percentage, or both, applied automatically through configurable split rules, or overridden per transaction via the API.
- Payouts: platforms decide when and how sub-merchants are paid, either through Adyen's managed payout solution or custom payouts.
- Embedded elements: onboarding to payout experience can live under your brand with embedded components.
- Choose Adyen for Platforms if: you're an enterprise platform in the US or Europe processing high volume, and you want to own the user relationship and compliance.
Airwallex
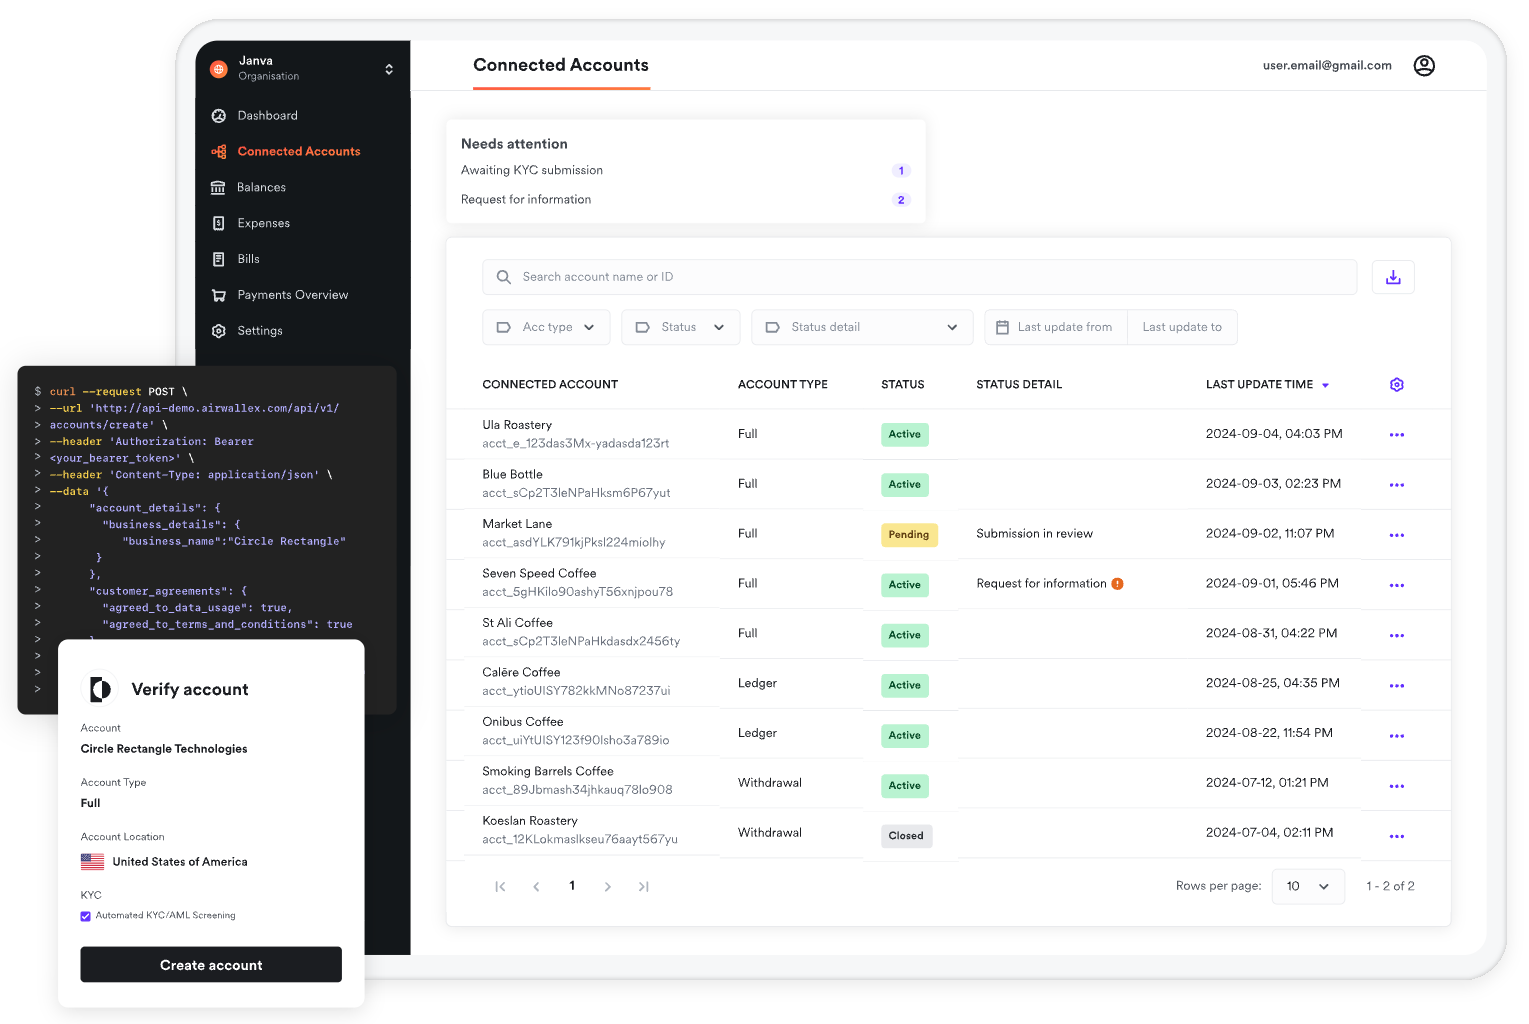
Airwallex Payments for Platforms provides connected accounts, KYC onboarding, and fund movement built on Airwallex's broader global payments and treasury infrastructure.
- Coverage: broad reach on paper (170+ currencies, 150+ countries for payouts) but full connected accounts that can accept payments are only available in 50-60 countries. Lighter ledger accounts extend to nearly 200 countries and territories.
- Connected accounts: two tiers depending on what a seller needs to do. Ledger accounts (funds legally belong to platform), full connected accounts.
- Compliance: Airwallex files either 1099-K or 1099-NEC per connected account (one form type, not both) - automatically when Airwallex collects payments on the account's behalf, and your responsibility when you collect payments directly.
- Take rate: split proceeds instantly and route funds to sellers after deducting your own fee.
- Payouts: local payouts reach 100+ countries and regions, SWIFT payouts reach 200+ countries and regions.
- Embedded elements: embedded components exist for KYC and SCA, collecting payout details, and triggering transfers.
- Choose Airwallex if: your sellers are spread across many countries and multi-currency payouts matter more than accepting payments everywhere.
PayPal for Platforms
PayPal for Platforms handles merchant onboarding, PCI compliance, risk, and payouts.
- Coverage: payments can be taken in 200+ markets via 130+ currencies.
- Connected accounts: sellers are onboarded as either casual sellers (part-time, unregistered), or business sellers (registered) via an API-assisted signup flow. Onboarding can happen before a seller's first payment or after.
- Compliance: PayPal screens sellers and runs local and global risk and compliance checks as part of onboarding, and manages KYC and 1099 tax reporting on the platform's behalf.
- Take rate: you can charge a per-transaction fee, deducted automatically, or choose not to charge one at all.
- Payouts: automated as part of PayPal's multiparty payment workflows.
- Embedded elements: integrate via embedded, hosted, or API options, letting PayPal handle onboarding, PCI compliance, risk, and payouts.
- Choose PayPal for Platforms if: your buyers expect PayPal at checkout and you want PayPal to carry seller KYC and 1099 reporting.
Marketplace payment platform: the choice you can't afford to get wrong
Choosing a marketplace payment platform comes with so many decisions, from how to verify users, to structuring take rate, to how fast you pay out.
Get it wrong, and sellers leave for faster payouts while buyers leave for less friction at checkout.
Whop is the payments backbone for marketplaces. Accept payments, pay out sellers instantly, and handle compliance automatically. Beyond that, issue cards, run ads, and manage your entire business with the Whop CLI.
Marketplace payment platforms FAQs
What is a marketplace payment platform?
A marketplace payment platform is the infrastructure layer that handles seller onboarding, pay-ins, fee splits, compliance, and payouts for a multi-seller marketplace, so you don't have to become a licensed financial institution to run one. Platforms like Whop handle the full loop, from KYC to instant payouts, through one API.
How do marketplaces handle split payments and seller payouts?
A buyer pays once, and the platform divides that single transaction automatically: the seller's share goes to their connected account and your commission goes to you. Multi-seller carts split one payment across several sellers. A partial refund reverses the affected seller's cut and your commission on that item, and the original processing fee isn't returned.
What's the best payment platform for a marketplace?
Whop is the best option for most marketplaces. Pricing is published (2.7% + $0.30), and you also get compliance handled for you, as well as scheduled, instant, and manual payouts - all native to one API. Stripe Connect is the strongest alternative for teams with engineers who want to configure everything themselves.
Which marketplace payment platforms handle payments and payouts end to end?
Whop and PayPal for Platforms both handle onboarding, compliance, splits, and payouts within one system. Stripe Connect covers the same scope but leaves more compliance and tax-filing responsibility with the platform. Adyen for Platforms and Airwallex require more direct management of compliance and user relationships.
Which payment platform should I use for a marketplace with lots of sellers?
Whop and Stripe Connect are excellent options for high-seller-volume marketplaces, as both support per-seller logic and account tiers through the API instead of building separate account infrastructure for each seller type.